You sold some Bitcoin last year. Maybe you mined a few blocks in Siberia. Or perhaps you just moved stablecoins around to dodge inflation. Now the Federal Tax Service (FTS) is knocking on your door, or at least, it will be when you file your next return. If you are holding digital assets in Russia, the days of treating them like invisible barter tokens are over. Since January 1, 2025, the rules have hardened. What used to be a gray zone is now a concrete legal framework under Federal Law No. 418-FZ. It’s not just about paying taxes; it’s about avoiding fines that can eat up half your profit.
Here is the reality check: Crypto is property. That sounds simple, but it changes everything. You don’t pay VAT on transactions anymore, which is good news for traders. But you do pay income tax on profits. And if you are a miner, you are looking at corporate rates that might make you rethink your setup. This guide breaks down exactly what you owe, who owes it, and how to keep the auditors happy without losing your mind.
The Core Principle: Property, Not Currency
Let’s get the definition straight because it dictates your tax bill. Under Russian law, cryptocurrency is property. It is not money. It is not a currency you spend at the grocery store (yet). Because it is property, any gain you make from selling it is taxable income. This aligns with the global trend, but Russia’s implementation has specific twists.
The biggest win here? VAT exemption. Before the new rules, there was confusion about whether buying and selling crypto triggered Value Added Tax. Some platforms charged it, others didn’t. Now, the law explicitly exempts crypto transactions from VAT. This lowers the friction for trading. However, this does not apply to services provided by exchanges or miners. If you buy hardware for mining, you still pay VAT on the equipment. If you sell electricity to a grid, different rules apply. But the act of swapping Bitcoin for Rubles? No VAT.
Tax Rates for Individuals: The 13% vs. 15% Split
If you are an individual resident of Russia, your tax rate depends on how much you earn. The system is progressive, meaning the more you make, the higher the percentage.
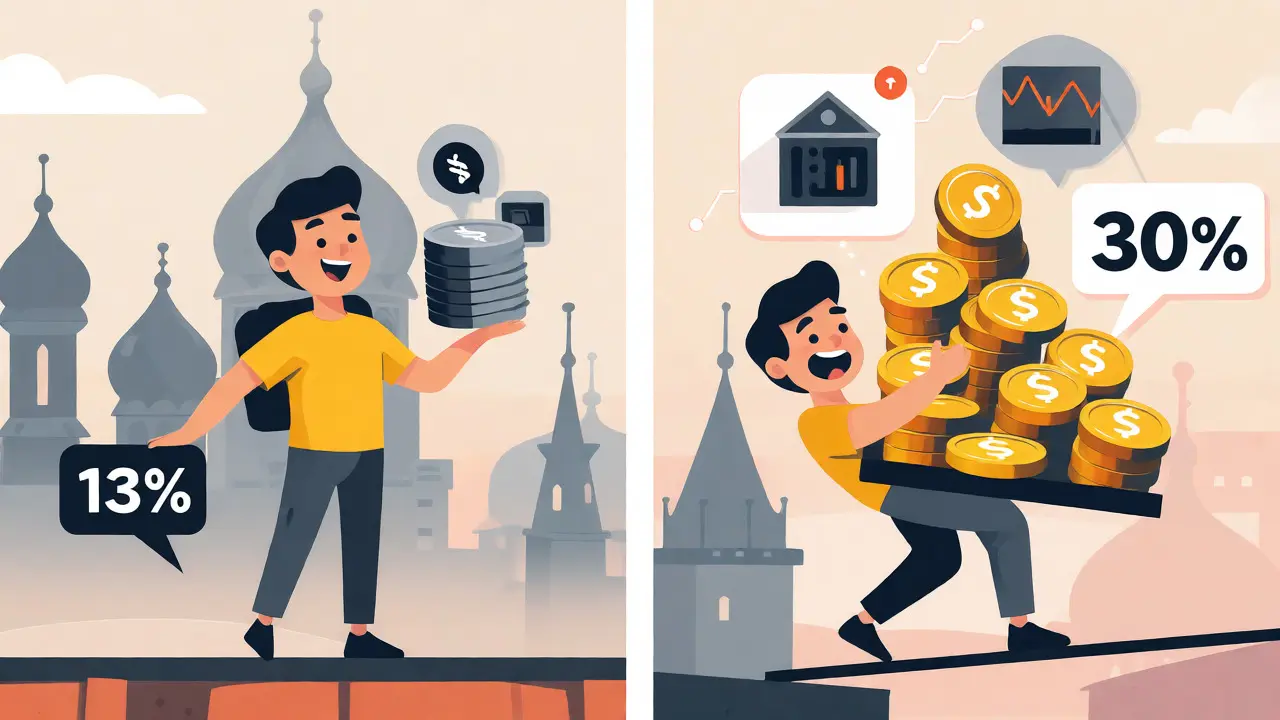
- 13% Rate: Applies to annual cryptocurrency income up to 2.4 million rubles (approx. $32,653).
- 15% Rate: Applies to the portion of your income exceeding 2.4 million rubles.
This isn’t calculated per transaction. It’s your total net profit for the year. If you made 1 million rubles in gains in January and lost 500,000 rubles in February, your taxable base is 500,000 rubles. You pay 13% on that.
What if you live abroad? Non-residents face a flat 30% tax rate on Russian-sourced crypto income. There is no threshold here. Every ruble of profit gets hit with 30%. This makes residency status critical. If you move to Dubai or Georgia but keep your Russian wallet active, ensure your tax residency is properly documented, or you might get stuck with the higher rate.
| Residency Status | Income Threshold | Tax Rate |
|---|---|---|
| Russian Resident | Up to 2.4M RUB | 13% |
| Russian Resident | Above 2.4M RUB | 15% |
| Non-Resident | All Income | 30% |
The Reporting Trap: The 600,000 Ruble Rule
Here is where people get tripped up. You don’t necessarily have to file a complex declaration for every tiny trade. There is a reporting threshold. If your total volume of crypto transactions exceeds 600,000 rubles ($8,163) in a calendar year, you must report it to the FTS.
Wait, did I say "volume"? Yes. This includes both buys and sells. If you bought 300k worth and sold 300k worth, you hit the limit. Even if you broke even and made zero profit, you still have to report. Why? Because the FTS wants to see the flow of funds. They want to know where the money came from and where it went.
Pavel Zryachikh, CEO of Garantex, pointed out that this rule hurts small investors. Many users trade small amounts frequently. Tracking these micro-transactions to prove they stay under the limit is a nightmare. If you miss the deadline, the fine is up to 40,000 rubles. That’s real money for a casual trader.
Mining: Corporate Taxes and Regional Bans
Mining is treated differently than trading. If you mine crypto as a business entity (LLC), you pay a 25% profit tax. This is higher than the standard corporate profit tax of 20%, which has frustrated many operators. Critics argue this drives mining underground or into neighboring countries.
Can you mine as an individual? Yes, but the lines are blurry. If you run one rig at home, you might get away with personal income tax rules. But if you have a warehouse full of ASICs, the FTS will likely classify you as a business. And businesses cannot use simplified tax regimes like USN for mining. You must use the General Taxation System (OSNO).
Then there are the geographic restrictions. Mining is completely banned in several regions until 2031:
- Dagestan
- Chechnya
- DPR/LPR territories
In other energy-rich areas like Irkutsk Oblast, Buryatia, and Zabaykalsky Krai, mining faces seasonal bans during winter months when the grid is stressed. If you operate in these zones, you need to pause operations during peak demand periods or risk heavy penalties.
How to Calculate Your Profit: The Exchange Quotation Problem
To calculate tax, you need a value for your crypto at the time of sale. The law requires using market quotations from foreign trading organizers. These exchanges must meet two criteria:
- Daily trading volume exceeding 100 billion rubles.
- Three years of publicly available quotation data.
This effectively points to giants like Binance, Bybit, or OKX. But what if you traded on a smaller platform? Or what if prices differed across exchanges? The FTS expects you to use a consistent method. Most accountants recommend using the closing price on the day of the transaction from a major exchange that meets the criteria.
There is no provision for deducting expenses for miners yet. If you spent 1 million rubles on electricity, you can’t subtract that from your revenue unless you are a registered business entity with proper accounting. For individuals, it’s gross proceeds minus cost basis. Cost basis is what you paid for the coin. If you mined it, your cost basis is often considered zero, making the entire sale amount taxable.
Common Pitfalls and How to Avoid Them
Based on feedback from forums and accountant surveys, here are the top mistakes Russians make with crypto taxes:
- Ignoring the Three-Year Rule: Unlike cars or apartments, crypto does not get a three-year ownership exemption. You pay tax even if you held the coin for ten years before selling.
- Forgetting P2P Transactions: Peer-to-peer trades are visible to banks. Large transfers trigger compliance checks. If you can’t explain the source of funds, the bank may freeze your account, and the FTS may investigate.
- Underestimating Transaction Volume: Remember, the 600,000 ruble threshold is for volume, not profit. Frequent small trades add up fast.
- Lack of Records: The FTS requires detailed records: wallet addresses, transaction IDs, timestamps, and exchange rates. Screenshots aren’t enough. Export CSV files from every exchange you use.
One user on RuTracker reported spending 37 hours calculating their January 2025 tax liability. Don’t let that be you. Use specialized software or hire a pro early in the year.
Looking Ahead: Digital Ruble and Future Amendments
The landscape is shifting. The Central Bank launched a pilot for the Digital Ruble in late 2025. While this is a CBDC and distinct from private crypto, its integration into welfare payments could normalize digital asset usage.
Furthermore, the State Duma is debating amendments to clarify the 600,000 ruble threshold. Currently, it’s ambiguous for users with multiple small transactions. Expect potential changes in 2026 that might raise the threshold or change how volume is calculated. Keep an eye on official FTS updates.
Also, cross-border settlements using crypto are gaining traction under experimental legal regimes. If you use crypto for international trade, consult a specialist. Sanctions complicate the banking side, but the tax side is becoming clearer.
Practical Checklist for Compliance
Before you file, run through this list:
- Did you export all transaction histories from every exchange?
- Did you identify the correct exchange quotations for valuation?
- Did you separate personal wallets from business wallets?
- Did you check if your mining region had seasonal bans?
- Did you verify your tax residency status?
- Did you calculate total volume to see if you crossed the 600k ruble reporting line?
Crypto taxation in Russia is no longer optional. It is mandatory, detailed, and enforced. The fines are steep, and the audits are getting smarter. Treat your crypto portfolio like any other investment asset: document everything, calculate accurately, and file on time.
Do I pay tax on crypto-to-crypto swaps?
Yes. In Russia, swapping one cryptocurrency for another is considered a disposal of property. You must calculate the profit based on the ruble equivalent of the coin you sold versus the coin you received. If the value increased, you owe tax on that gain.
Is there a tax-free allowance for crypto losses?
You can offset losses against gains within the same tax year. If you lose money on one trade and make money on another, you only pay tax on the net profit. However, you cannot carry forward losses to future years under current regulations, so plan your sales strategically.
What happens if I fail to report my crypto income?
Penalties include fines of 20-40% of the unpaid tax amount plus interest. Additionally, failing to submit the required information about crypto holdings when requested by the FTS can result in administrative fines up to 40,000 rubles. Repeated offenses may lead to criminal liability for large sums.
Can I deduct mining electricity costs as an individual?
Currently, individuals generally cannot deduct operational costs like electricity for mining unless they are registered as self-employed or as a business entity with proper documentation. For most hobbyist miners, the tax base is the sale price minus the acquisition cost (often zero for mined coins), making deductions difficult to claim.
Does the 600,000 ruble threshold apply to profit or transaction volume?
It applies to the total transaction volume (turnover) of cryptocurrencies during the year, not just the profit. This includes both purchases and sales converted into rubles. Even if you break even, exceeding this volume triggers a reporting obligation.
Leave a comments